There’s a common piece of advice floating around: “get a master’s, it’ll pay off.” There’s also an equally common counter-narrative: “grad school is a debt trap.” Both are true, just not for the same degree, the same field, or the same person. If you’re weighing whether to go back to school, the real answer isn’t a vibe; it’s math, and the math looks very different depending on what letters you’re chasing after your name. Here’s a full, evidence-based breakdown.
The Good News: The Earnings Premium Is Real
Let’s start with what the data clearly supports: on average, more education still correlates with more money. The Bureau of Labor Statistics reports median usual weekly earnings of $1,661 for master’s degree holders versus $1,432 for bachelor’s degree holders, an annualized premium of roughly $11,900 a year, or about $476,000 over a 40-year career, before taxes and debt payments are factored in. Zoom out further, and one comprehensive study found that having an advanced degree boosts median earnings by about 29.68%, from $66,410 with just a bachelor’s to $86,120.
That’s the topline. But the real story is in the variance, and this is where things get interesting.
The Fields Where Grad School Basically Guarantees a Return
Not all master’s degrees are created equal. One of the more rigorous ROI studies out there found that master’s degrees in engineering, computer science, and nursing virtually guarantee their graduates a positive financial return. In STEM specifically, workers with a master’s degree earn a median of $105,000 a year, compared to $75,000 for bachelor’s holders in the same fields, a roughly 40% bump.
Professional and doctoral degrees can go even further. Professional degrees in law, medicine, and dentistry often have a payoff exceeding $1 million over a career. And in the private sector, PhD holders in computer science, engineering, economics, and other quantitative fields typically out-earn master’s-degree holders by $30,000 to $60,000 a year. And for a median master’s degree across all fields? One large-scale analysis put the number at a positive $83,000 increase in lifetime earnings, after subtracting the full cost of grad school.
So far, so good. But that median is hiding a much messier picture underneath it.
The Bad News: Almost Half of Master’s Degrees Don’t Pay Off
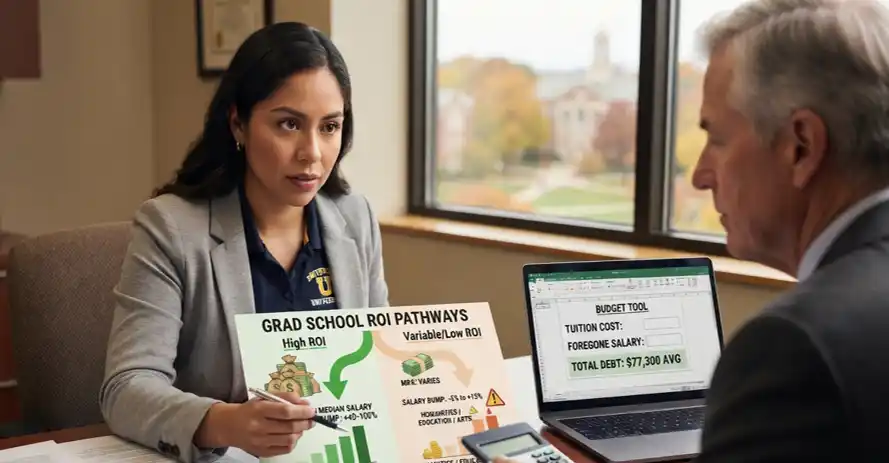
Here’s the number that should make anyone pause before enrolling: 40% of master’s degrees fail to produce a positive return at all, according to comprehensive ROI research, and a separate analysis puts the figure at “nearly half” once you account for tuition and modest salary bumps. Even the MBA, one of the most popular graduate degrees in America, “frequently has a low or negative payoff.”
The fields that struggle most are fairly predictable: arts and humanities programs “rarely pay off at all,” and broader guidance on master’s-degree ROI flags education, social work, and parts of the humanities as areas where the salary bump typically doesn’t justify the tuition plus two years of lost income. One ranking of college majors even found that a couple of fields such as family & consumer sciences and psychology have graduates whose modeled 10-year earnings actually trail those of a typical high school graduate.
The Debt Numbers Are Not Small
This is where the real risk lives. According to recent data:
- The average graduate student finishes school owing about $77,300, and combined with undergraduate loans, that climbs to $88,220.
- By degree type: medical graduates average nearly $192,000 in debt, law graduates about $133,000, master’s degrees around $53,920, and MBAs about $51,850.
- The Federal Reserve’s own household survey found that adults carrying graduate-school debt owe a median of about $57,500: enough, researchers note, to meaningfully constrain housing choices, family planning, and career flexibility for years afterward.
And the financing landscape is getting tighter, not looser. The federal Grad PLUS loan program, which used to let students borrow up to the full cost of attendance, is sunsetting for new borrowers as of July 1, 2026. Going forward, annual federal borrowing is capped at $20,500 for most master’s programs and $50,000 for professional programs like law and medicine, meaning more of the gap will likely need to be covered by private loans, savings, or employer support.
The Cost People Forget: Time
Sticker price is only half of the actual cost. A full-time graduate program usually means one to several years of foregone salary on top of tuition, and for professional or doctoral tracks, that adds up fast. Total costs, once you include lost earnings, loan interest, and (for some fields) years of licensing or residency requirements, “can change dramatically” from what the tuition bill alone suggests.
Academia carries its own version of this risk. PhD students banking on a professorship should know that tenure-track assistant professor salaries range from about $60,000 in the humanities to $130,000 in business and engineering, and in many humanities fields, fewer than 30% of PhD graduates land a tenure-track position at all.
So… Is It Worth It? The Real Answer
Based on the evidence, “is grad school worth it” isn’t one question, rather five smaller ones stacked together:
- Is your field one where demand and pay are strong? Engineering, CS, nursing, healthcare administration, and most quantitative PhDs: strong odds. Humanities, and some education/social-work master’s: much weaker odds.
- Does the career actually require the credential? Law, medicine, clinical psychology, and academia aren’t really “ROI” questions. The degree is the entry ticket, full stop.
- How much is the specific program actually going to cost you? Research on this is blunt: a $40,000/year degree from a $25,000-total program can beat a $90,000/year degree from a $280,000-total program. The brand name on the diploma often matters far less than people assume. For most technical, healthcare, and education fields, program cost and accreditation matter more to salary outcomes than school ranking does.
- Can you do it without quitting your job? Earning a degree part-time while working sidesteps the single biggest hidden cost: years of lost salary.
- How are you financing it? Debt-financed degrees in low-payoff fields are the riskiest combination in this entire analysis, marked by high fixed cost and uncertain return.
The bottom line: the “average” answer is mildly positive, but averages are actively misleading here, because outcomes for a computer science master’s and a fine arts master’s aren’t in the same universe financially. The smart approach isn’t asking whether graduate school is worth it in the abstract, it’s running the specific numbers (program cost, expected salary bump in your target field, and financing terms) before you commit. Be wise and choose wise.
References:
- U.S. Bureau of Labor Statistics; FREOPP (“Is Grad School Worth It? A Comprehensive Return on Investment Analysis”)
- Federal Reserve Survey of Household Economics and Decision making (SHED)
- National Center for Education Statistics
- Georgetown University Center on Education and the Workforce